Home Blog

Have You Paid Through Mercuryo Without Knowing It? Arthur Firstov Explains
0
Have You Paid Through Mercuryo Without Knowing It? Arthur Firstov Explains

Many people who have bought crypto inside a wallet app have used Mercuryo without ever seeing its name. The “buy crypto” button looks like part of the wallet. Behind it, a separate company handles the identity checks, the fraud screening, the licences and the movement of money. That hidden layer is the business Mercuryo has built, and according to one of its senior executives, it is where much of the payments industry is heading as stablecoins move from trading into everyday use.

On the sidelines of Token2049 in Singapore, Amreen of The Blockopedia sat down with Arthur Firstov, Chief Business Officer at Mercuryo, for the TBP Podcast. Amreen introduced Mercuryo as the company quietly powering the crypto button inside large wallets such as MetaMask, Tangem and the Bybit wallet. Over ten minutes, the conversation covered how Mercuryo moved from cross-border payments into stablecoins, the most common mistake companies make with banks and payment partners, where in Asia stablecoins are entering daily use, why payroll and remittance companies now want crypto payment products, and his advice for a first purchase.

Key Takeaways

  • Mercuryo is built to be invisible. Arthur says the product is “fully API, fully white label”, so wallets and apps offer crypto payments under their own brand while Mercuryo handles identity, fraud and compliance.
  • The company started with cross-border payments for crypto businesses. Stablecoins came later, adopted first by businesses as a faster and cheaper way to settle with each other, then more slowly by retail users.
  • The most common mistake firms make with banks and payment partners, he says, is a lack of communication. Trust takes time to build.
  • Arthur calls Asia and the wider APAC region a “super interesting corridor”, where businesses already use stablecoins day to day and build payment routes to the US, Latin America, Europe and the Middle East.
  • Mercuryo’s focus for the next 12 months stays the same, but its customers now include payroll firms, remittance companies and large payment providers testing crypto payouts and deposits.
  • His advice before a first purchase: use a trusted, widely used app in your region, be aware of scams, and do not invest before you understand what you are buying.

From cross-border payments to stablecoins

Amreen opened by noting that Arthur has been in crypto since 2017, when stablecoins were still a boardroom topic. What pulled him into this side of the industry?

Arthur says Mercuryo’s path was different in terms of use cases. The company started with a simple idea: build cross-border payments for crypto companies and the wider digital asset economy. Stablecoins, he says, came a little after the team decided to build that product.

In the early years, most activity was speculative. People wanted to buy crypto with their bank accounts, or sell it. Then Mercuryo watched stablecoin adoption grow, starting with businesses rather than individuals. Companies found that stablecoins were a “faster, easier and cheaper way to do the cross-border settlements and payments to each other,” he says.

Retail users followed more slowly. Today, Arthur points to remittance firms, payroll companies, new banks and fintechs that offer stablecoins as a main product. For Mercuryo, he describes the change as a slow shift rather than a sudden pivot.

Mercuryo was founded in 2018, according to its own website. Its company profile on CryptoSlate says it first launched as a wallet for buying crypto with a bank card, then moved to an infrastructure-first model in 2019, supplying payment and compliance technology to other platforms. Its co-founder and chief executive is Petr Kozyakov.

What is Mercuryo? The payment button you never see

Most people, Amreen said, have used Mercuryo without ever seeing the name inside the wallet. How would Arthur explain the company to someone hearing about it for the first time?

He describes Mercuryo as a software company that holds the licences and runs compliant, regulated infrastructure. That infrastructure lets others offer financial products, fintech services and neobanking experiences to crypto-native users and crypto-native companies.

The invisibility is deliberate. “Somebody never saw it and never understood that they made a transaction with Mercuryo,” he says. “But in reality we built the product the way that it’s fully API, fully white label.”

White label means the partner puts its own brand on the experience. The user stays inside the wallet or app they already trust. Mercuryo sits in the background and, in Arthur’s words, automates and abstracts away many of the components a company would otherwise need to build a financial stack on stablecoins. He gives examples:

  • the identity layer, meaning know-your-customer (KYC) checks
  • fraud checks
  • regulation and compliance questions that change from one jurisdiction to another

Partners reach these services through APIs and present them as their own. Arthur compares the goal to the native payment experience people already know from apps such as Uber and Grab.

The simplest example is an on-ramp: the step where a user turns ordinary money, such as euros on a bank card, into crypto. Mercuryo’s website says its on-ramp has more than 12 million KYC-verified users, is available in 150 countries and is used inside more than 500 apps, with partner logos including MetaMask, Trust Wallet, Ledger, Bybit and Tonkeeper.

The most common mistake: a lack of communication

Amreen asked what the most common mistake is when crypto companies try to partner with banks or payment companies.

Arthur’s answer is plain. “It’s just a lack of communication in the first place,” he says.

He widens the point beyond crypto. Many businesses have never worked closely with a payment company. They know how to add a Stripe link to accept payments. But cross-border payments, bank accounts and settlement in different currencies are a different matter. “I think it’s really hard and complicated to navigate how it works and who is the best partner for it,” he says.

Even with conferences and heavy marketing, he says, the core problem is still communication: getting a partner to know your brand, and to trust your brand with their money. Arthur says it takes quite some time to build that awareness first, and then the trust needed between a payments provider and a crypto firm, enterprise, fintech or bank before a payment product launches. That is especially true now for stablecoin and crypto payment products.

Which Asian markets are pulling stablecoins into everyday use?

With the interview recorded in Singapore, surrounded by Asian founders and builders, Amreen asked which market is pulling stablecoins into everyday use.

Arthur starts with the United States. There, he says, regulation has pushed many payment companies, banks and financial institutions to adopt crypto, digital assets and stablecoins, and bigger brands are making moves.

Asia looks different to him. In Singapore, for example, he sees a very large number of businesses that were already using stablecoins for day-to-day operations. He calls Asia, and APAC in general, a “super interesting corridor”. Businesses in the region are building international companies and payment corridors with the US, Latin America, Europe and the Middle East, and they are looking for the best partners to do it.

“I think stablecoin adoption here is pretty huge,” he says, linking it to Token2049 itself, which he notes draws more attendees every year and felt even busier this time.

Mercuryo’s own figures point in the same general direction, though they are global rather than Asia-specific. In a July 2026 press release, the company said stablecoins made up 60% of total crypto purchase value through its on-ramp in the first half of 2026, up from 43% in the second half of 2025. Stablecoins also accounted for 47% of first-time crypto purchases, compared with 33% six months earlier.
Spend, the co-branded crypto card product cryptopowered by Mercuryo
Spend, Mercuryo’s co-branded crypto card product for wallets and apps. Image: Mercuryo (mercuryo.io).

Mercuryo’s next 12 months: same focus, new customers

Asked about Mercuryo’s biggest focus for the next 12 months, Arthur says the core mission has not changed. The company has always worked on products that let people move money and value across countries, assets, chains, platforms and financial institutions. “So, the focus remains the same,” he says. In practice, that means polishing the products and offering partners more customisable experiences.

What has changed is who is asking. “Before it was only crypto companies,” he says, meaning crypto-native enterprises such as wallets, exchanges and brokers. Those firms are still customers. But Arthur sees many newcomers built around new narratives, including prediction markets, decentralised exchanges, perpetual futures DEXs and other trading platforms. They need the same type of products Mercuryo already builds.

Mercuryo’s product range has widened to match. Its website lists on-ramps, swaps, pay-ins, pay-outs and Spend, a co-branded card product it launched with Mastercard in 2024. In March 2026, Mastercard named Mercuryo among the more than 100 companies in its new Crypto Partner Program. In October 2026, FF News reported that Mercuryo launched cross-chain swaps and ran a zero-fee on-ramp offer for new MetaMask users in Canada.

Why payroll and remittance firms now want crypto rails

The bigger shift, Arthur says, is demand from traditional financial institutions. The products Mercuryo builds for crypto firms are now “widely demanded” by traditional players too. He names payroll companies, remittance firms and the “PayPals of this world”.

Rather than rebuilding around crypto, many are launching one part of it, “just to test the waters”. His examples include payouts in crypto and deposits in crypto, and the video’s chapter notes add cards and ramps to that list.

It is the same pattern Arthur described with stablecoins: businesses move first, and consumers follow. Looking further ahead, he expects industries well beyond finance, payments, fintech and crypto to adopt the same technology and offer those experiences to their own users. “Slowly and slowly” is how he puts the pace. That is a forecast from someone who sells this infrastructure, not a trend that has already played out at scale.

Advice before your very first purchase

Amreen’s last question: what is the one piece of advice for someone about to make their very first purchase?

Arthur says it depends on the platform and on what the person wants to do. Many people today want to buy stablecoins to send money to family, to friends in another country, or to business counterparties. For that use, he says, stablecoins are the easiest way.

His practical advice is to “find the best partner, the best consumer interface, the wallet, the app” that is widely used by people in your region. He expects the major ones already offer crypto and use stablecoins. Even long-standing firms such as MoneyGram, PayPal and Western Union, he says, are moving into stablecoins and crypto, so people can use them where available.

Then comes the warning. “Be aware of scam. Don’t invest before you know something,” he says.

He closes by saying that stablecoins feel like a fairly safe experience, especially with trusted brands. That is his view, and it has limits. A stablecoin is only as sound as its issuer and reserves, prices can slip from the peg, and scammers often copy the look of well-known apps. A trusted app reduces some of those risks but does not remove them.

Final thoughts

The interview makes one point clearly: some of the most important companies in crypto payments may be the ones users never see. Mercuryo’s model is to hold the licences, run identity, fraud and compliance checks, and let wallets, exchanges and now traditional payment firms put their own brand on the result. Its own data, showing stablecoins at 60% of on-ramp purchase value in the first half of 2026, supports Arthur’s view that stablecoins are moving from trading towards payments.

Some of what he said is forecast rather than fact. His expectation that industries far beyond finance will adopt these rails, and his read on APAC as a key stablecoin corridor, are informed views from inside the industry, not settled outcomes. First-time buyers should follow his own advice: use a trusted app, watch for scams, and understand what they are buying first.

Watch the full conversation on the TBP Podcast YouTube channel.

Frequently Asked Questions

Q: What is Mercuryo?

Mercuryo is a crypto payments infrastructure company founded in 2018. It provides on-ramps, swaps, pay-ins, pay-outs and co-branded crypto cards that wallets, exchanges and apps offer under their own brand. Arthur Firstov describes it as a licensed, regulated software company whose products are fully API-based and white label.

Q: Why do people use Mercuryo without seeing its name?

Because the product is white label. A wallet or app shows its own buy button, while Mercuryo handles identity checks, fraud checks, compliance and the payment in the background. Arthur says many users never realise they made a transaction with Mercuryo.

Q: What mistake do crypto companies make when partnering with banks and payment firms?

Arthur says the most common mistake is a lack of communication. Cross-border payments, bank accounts and foreign exchange settlement are hard to navigate, and building awareness and trust with a partner takes time.

Q: Which region does Arthur Firstov see driving everyday stablecoin use?

He points to Asia and the wider APAC region, using Singapore as an example. He says many businesses there already use stablecoins day to day and are building payment corridors with the US, Latin America, Europe and the Middle East.

Q: What kinds of companies now want stablecoin payment products?

Beyond wallets, exchanges and brokers, Arthur sees demand from prediction markets, decentralised exchanges and trading platforms. He also names payroll companies, remittance firms and large payment providers testing crypto payouts and deposits.

Q: What should I do before my first crypto or stablecoin purchase?

Arthur advises using a trusted wallet or app that is widely used in your region, being aware of scams, and not investing before you understand what you are buying. This is general information, not investment advice. Crypto assets are volatile, stablecoins carry issuer and peg risks, and you can lose money.
Can One Person Change Cardano? Intersect’s Jack Briggs Explains

0
Can One Person Change Cardano? Intersect’s Jack Briggs Explains

Most blockchains change slowly. Upgrades can take years of debate, and the people who hold the tokens rarely get a direct say. Cardano has taken a different route. Its community now proposes and votes on changes on-chain, and one organisation sits in the middle of that process, helping ideas turn into decisions.

On the sidelines of Token2049 in Singapore, Mohammad Ahmad Khan, co-founder of The Blockopedia, sat down with Jack Briggs, Executive Director of Intersect, for the TBP Podcast. Intersect is the member-based organisation that coordinates decision-making for the Cardano ecosystem. In a 10-minute conversation, Jack explained why he chose Cardano, how a proposal moves through Intersect, how builders can get funding, how he went from buying his first Bitcoin in 2012 to leading Intersect, and where he sees the next wave of innovation.

Key Takeaways

  • Intersect is a member-based organisation that helps Cardano make decisions. Members find a problem, propose a solution to the ecosystem, the community votes, and then the change is made.
  • By Jack’s estimate, Intersect has proposed about 80% of all the votes Cardano has taken. Its elected expert committees help ideas win wider support.
  • Cardano is permissionless, so anyone can propose a change. Jack says one community member pushed a major change through last year, which shows a single voice can still matter.
  • Builders on Cardano are funded through the on-chain treasury, outside capital or their own money. No permission is needed to build, and Intersect and the founding entities can offer extra support.
  • Jack says Cardano is “catching up” from a position of strength, pointing to new integrations such as LayerZero and Fireblocks and to the chain’s record on security.
  • He believes the same tools could make government more transparent, and names AI agents, DeFi and privacy, including the Midnight network, as the main areas of innovation.

Why Cardano? Academic rigour and security

The first question was the simplest one: why Cardano? Jack points to how the network was built. For him, the core reason for its success is “its academic rigour and how it was built in the first place.”

He describes Cardano as one of the longest-standing blockchains, one of the “legacy” layer 1 networks from 2017 and 2018. It is, he says, “still very much alive and kicking and importantly safe and secure.”

That matters more now, he argues. With the rise of AI and problems hitting many different protocols, Jack says Cardano is holding itself above the rest on security and resilience.

His second reason is what developers can do on the chain. “The programmability of it is immense and deep,” he says.

What Intersect does for Cardano

Jack is direct about how he sees his organisation. “Intersect is a very unique company,” he says. “It’s probably actually unique in the whole of the industry. There’s not a company quite like us anywhere else.”

Its job, in his words, is to “help coordinate decision-making.” Intersect is a member-based organisation. Members join, and those members bring forward ideas for the rest of the ecosystem to consider and vote on.

Intersect launched in July 2023 as a member-based organisation to steward Cardano’s development, according to Input Output’s timeline of Cardano governance. Since the Chang upgrade in September 2024, Cardano has run on-chain governance. Cardano Docs says any ada holder can now submit or vote on governance actions, either directly or by delegating to representatives known as DReps.

Jack contrasts this with older networks. Because Cardano’s community can find consensus together quickly, vote and then act, he says it can move faster than Bitcoin or Ethereum on big questions. “Cardano can move at light speed with big decisions,” he says. He calls that “massively important” for how the network keeps advancing, “especially in the age of AI.”

How a proposal moves through Intersect

Jack describes the basic loop in a few steps:

1. Members join Intersect.

2. They find a problem.

3. They find a solution.

4. They propose it to the rest of the ecosystem.

5. The community votes.

6. If the vote passes, the change is made.

“And that can happen pretty quickly, actually,” he says.

Ahmad asks for a real example of a decision that would not have been possible without Intersect. Jack starts with a key point about Cardano: it is permissionless. “Anyone can suggest anything and it can happen,” he says. “The challenge is when you build consensus so that people support that idea.”

That is where Intersect plays its biggest role. By Jack’s estimate, Intersect has proposed about 80% of all the votes Cardano has taken. Part of the reason is expertise. Intersect has elected committees, and their members typically have backgrounds in technology, growth, adoption or utility.

Proposals that come from these experts tend to win more consensus, he says. Voters like the fact that “someone else has looked at this” and that “it’s not just some one person’s idea.”

Yet the system does not lock out individuals. Jack says one community member proposed “a massive change to the ecosystem” last year, and it went through. He did not name the proposal in the interview. For him, that is the point. An institution like Intersect can help many decisions through, while “one person with one voice and a bit of grit can make a change as well.”

“And that’s just the beauty of Cardano,” he adds.

Advice for builders: funding and support

Asked what builders should know if they want approval in the Cardano ecosystem, Jack is open that this is “probably a challenge that we are still working through.”

Today, he says, Cardano builders fund their work in one of three ways:

  • the Cardano treasury, which he calls one of Cardano’s “big USPs”
  • external capital raised elsewhere
  • their own money

There are no gatekeepers. “You don’t need permission to build on Cardano, anyone can,” Jack says. Builders who want more institutional backing can turn to Cardano’s founding entities or to Intersect. But he stresses that there are “no rules” and “no criteria” to build on Cardano, which he sees as “really important” so that anyone can come.

The bigger question for Cardano, Jack says, is how it attracts builders, and that is where governance has changed things. He points to LayerZero and Fireblocks coming on board. “Cardano is very much catching up,” he says. “And when I say catching up, we’re catching up from a position of strength.”

His case rests on the same strengths he named earlier: academic rigour, security and a resilient chain. Builders want to build there, he says, because they know their smart contracts “are going to be deployed safely and they’re going to work.”

Both integrations are on public record. LayerZero, a protocol that lets blockchains pass messages and assets to each other, went live on Cardano in March 2026, connecting it to more than 160 other chains, according to TapTools. The integration came through a Critical Infrastructure proposal backed by the Cardano “Pentad”: the Cardano Foundation, Input Output Global, EMURGO, Intersect and the Midnight Foundation.

In September 2026, the Cardano Foundation and Fireblocks also announced that Cardano Native Tokens will be fully supported on the Fireblocks platform, with support expected by March 2027. Fireblocks has supported ADA itself since 2021, according to the Cardano Foundation.

Intersect website banner: Building Together to Drive Cardano Forward, with the tagline Uniting the Cardano Ecosystem
Intersect’s website banner, with the tagline “Uniting the Cardano Ecosystem”. Image: Intersect (intersectmbo.org).

From a £52 Bitcoin to leading Intersect

Ahmad then turns to Jack’s own story. Jack got into Bitcoin in 2012, out of simple curiosity. “I spent 52 pounds, I think, on my first Bitcoin,” he recalls. He says he moved into Ethereum around 2015 or 2016, and Cardano “came quite naturally afterwards.”

His route into Cardano work came through an offer from one of its founding entities, the one led by Charles Hoskinson. The task was to help shape the future of Cardano, and to work out how to coordinate an ecosystem as decentralised and global as Cardano.

His LinkedIn profile shows that he led product marketing for Cardano’s governance era at Input Output from late 2021. He joined Intersect as Ecosystem Director in January 2024 and became its Executive Director in 2025. Before crypto, he worked in marketing for firms including Vodafone and Thomson Reuters.

The role felt natural, he says, because of where he came from. London, in his words, is “a well-established democracy, but like all democracies has problems.” Jack was frustrated with the issues he saw locally in London and nationally in the UK.

He wanted “a different way of how do we govern ourselves,” and a way to make decisions “more transparently, more openly together.” He also wanted to stop relying on information from an institution he does not trust.

“I don’t need to trust, I can verify myself,” he says, calling that the whole point of blockchain.

That thinking drew him to Intersect. He helped build it, incubate it and launch it. Now he runs it.

Can Cardano’s model work for governments?

Ahmad asks how the system Jack has helped build on Cardano could work in real life. Jack, who now lives in Spain, starts with his own paperwork. Every time he renews a licence or a permit, he says, “I have to sit in a room for 6 hours.” He describes being sent from room to room, then finding out he has missed something and needs another stamp.

He believes blockchain is ready to change national infrastructure, and says it “just makes no sense why we don’t do it.” His case is about money and openness. It would save taxpayers a great deal of money, he argues, and it would bring transparency.

“I want to know where my taxpayer money is being spent, and I want to know how decisions are being made,” he says. In his view, that is missing in national governments everywhere, and no country is an exception. “India is the same, US has problems, we’re all the same,” he says.

Where Jack sees the innovation: AI agents, DeFi and privacy

Ahmad’s last question asks for two pieces of advice for builders: where to go, and what to be cautious about, given that Jack has seen several market cycles. Jack’s answer focuses on the opportunities. He does not name areas to avoid.

He starts with agentic AI, while admitting “that’s the buzzword now.” His main pick, though, is DeFi. “DeFi is where the innovation, the financial innovation really is,” he says.

When traditional finance looks at blockchain and asks where new ideas in finance are coming from, the answer, he says, is DeFi. That is why the industry is seeing more TradFi interest, and he argues it is about more than liquidity or yield opportunities.

“You can get lost in DeFi and come out like, ‘Wow, I didn’t know this was even possible,'” he says. What excites him most is doing it on his own terms. “I don’t have to ask permission to do something.”

His second pick is privacy, which he expects to be “a massive play.” He credits Zcash for doing well and pioneering the area. On Cardano, he points to Midnight. He calls it “the biggest project I would argue on Cardano at the moment” and a privacy play that everyone “should be excited about and all should care about as well.”

Midnight is a privacy-focused network in the Cardano ecosystem that uses zero-knowledge proofs. According to the Midnight Network blog, its mainnet was set for late March 2026, starting with federated node operators that include Google Cloud and Blockdaemon.

Final thoughts

The interview makes one point clearly: on Cardano, governance is not a side feature but the way the network moves. Jack describes Intersect as an organisation that helps members turn problems into proposals and builds expert-backed consensus, while still leaving room for a single member with “a bit of grit” to change things.

Some of what he says is fact and some is opinion or forecast. The LayerZero and Fireblocks integrations are on record. The 80% share of votes is Jack’s own estimate, and his views on government use, DeFi and privacy are predictions, not outcomes. He is also candid that support for builders is still being worked out.

Watch the full conversation on the TBP Podcast YouTube channel.

Frequently Asked Questions

Q: What is Intersect in the Cardano ecosystem?

Intersect is a member-based organisation that helps coordinate decision-making for Cardano. Members bring forward problems and solutions, propose them to the wider ecosystem, and the community votes. It launched in July 2023, according to Input Output.

Q: Who is Jack Briggs?

Jack Briggs is the Executive Director of Intersect. He got into Bitcoin in 2012, later worked on Cardano governance at Input Output, and helped incubate and launch Intersect before taking the top role.

Q: How does a proposal pass in Cardano governance?

Anyone can suggest a change because Cardano is permissionless. The proposal is put to the ecosystem and voted on. Jack says Intersect, supported by its elected expert committees, has proposed about 80% of all the votes Cardano has taken.

Q: Can one person change Cardano?

Jack says yes. According to him, one community member proposed a large change to the ecosystem last year, and it went through. Building consensus is the hard part, he adds.

Q: How do builders get funding on Cardano?

Jack says builders use the Cardano treasury, external capital or their own funds. No permission is needed to build. Intersect and Cardano’s founding entities can offer more institutional support.

Q: What is Midnight on Cardano?

Midnight is a privacy-focused network in the Cardano ecosystem that uses zero-knowledge proofs. Jack calls it arguably the biggest project on Cardano right now. This is an industry view, not investment advice – crypto assets are volatile and can lose value.

What Does It Take to Build Crypto Rails Banks Trust? Aquanow’s Andy Leung Explains

0
What Does It Take to Build Crypto Rails Banks Trust? Aquanow’s Andy Leung Explains

Banks do not want to build a crypto desk from scratch. They want someone else to handle the wallets, the compliance and the settlement, to banking standards. That is the business Aquanow has built since 2018, and one of its co-founders says the biggest lesson was that good technology alone does not win the deal.

On the sidelines of Token2049 in Singapore, Mohammad Ahmad Khan, co-founder of The Blockopedia, sat down with Andy Leung, CTO and co-founder of Aquanow, for the TBP Podcast. Over about 18 minutes, they covered Andy’s move from bank capital markets into crypto, what Aquanow does for banks, its stablecoin partnership with Visa, its UAE licence, why crypto rules differ so much between countries and what keeps ordinary people from using crypto.

Key Takeaways

  • Aquanow started in Canada in 2018 as B2B trading infrastructure, bringing a capital markets idea, liquidity aggregation, to crypto.
  • It sits behind banks and other financial firms, handling wallets, compliance and other crypto complexity so clients mainly integrate its API.
  • Andy says being only a technology provider was “not good enough”. Aquanow grew into a full-stack service covering onboarding, compliance, trading, settlement and custody.
  • In its partnership with Visa, Aquanow uses stablecoins to offer better prices and faster cross-border settlement. Andy says bank-grade infrastructure and a strong compliance team made the case.
  • He credits the UAE regulator’s work with industry for giving financial institutions confidence, and expects other countries to build their own frameworks over time.
  • The biggest gap, in his view, is retail adoption. Wallets and user experience still create friction, while business adoption grows first.

From bank trading desks to crypto liquidity

Before Aquanow, Andy worked in bank capital markets, with exposure to equities, fixed income and FX. He and two fellow co-founders all came from that world. According to Aquanow’s website, Andy was previously a vice president of electronic trading at RBC Capital Markets, and he studied at the University of British Columbia and the University of Toronto.

At the banks, one problem they worked on was liquidity fragmentation. Put simply: how do you pull together liquidity from many different exchanges and offer one deep pool of it to banks and their clients? When the founders started Aquanow in Canada in 2018, they took the same idea to cryptocurrency. The market was new, and liquidity aggregation barely existed.

The plan was to build B2B trading infrastructure for financial institutions, but in Canada, Andy notes, financial institutions still have not offered crypto directly to their end clients. So in the first two or three years, Aquanow found other customers at home, including exchanges and robo-advisors. It built API solutions and integrated with these firms. “We were kind of the liquidity provider behind the scene,” he says.

After winning what he calls a pretty good market share in Canada, the company expanded abroad, first to Turkey, then the UAE, and now Asia. The UAE, he says, is one of its biggest and most focused markets today.

What Aquanow does for banks

Ahmad asks Andy to explain Aquanow as simply as possible. “Aquanow is a B2B trading infrastructure,” he answers. The product sits behind financial institutions and other business clients.

The idea is to hide the hard parts. Crypto brings operational and technical complexity, from wallets to compliance. When a client integrates with Aquanow, Andy says, Aquanow handles those pieces for it.

For a bank, that changes the staffing question. “They don’t have to have a crypto team,” he says, meaning a team whose skills sit outside the bank’s existing business. “What they need to do is just integrate with our API,” and then work with Aquanow on any customised workflows the bank requires.

Over time, the offer widened. In the UAE, Aquanow began providing what Andy calls an enterprise-level, full-stack crypto solution for banks, covering:

  • onboarding
  • compliance
  • trading
  • settlement
  • custody

He describes this as the move from a pure liquidity provider to a full-stack enterprise solution, built for high availability and low latency. The newest product line is cross-border payments, which he says is quite different because it means licences in different jurisdictions, local payment partners and compliance in each market.

According to a November 2025 report by Electronic Payments International, Aquanow serves banks, neobanks, brokerages and payment companies, and employs more than 170 people across its global offices.

Why being a technology provider was not enough

One of the most candid points comes almost as an aside. When Aquanow started, Andy says, it was purely a technology provider. As it moved into new markets, the team learned that “only being a technology provider is not good enough” to serve a broader customer base.

So compliance, legal and regulatory expertise became part of the product. The goal, he says, is for customers to come to Aquanow “as a one-stop shop”, with a team that can answer their questions about entering new corridors. This matters most for payments, where each corridor, the route money takes between two countries, comes with its own rules.

The Visa partnership: stablecoins for faster cross-border settlement

Ahmad asks how Visa came to choose Aquanow for settlement in stablecoins. Andy places the deal in a wider trend: both Visa and Mastercard are moving into stablecoin solutions. He points out that Mastercard has acquired BVNK, a stablecoin infrastructure company. Mastercard’s quarterly filing with the US Securities and Exchange Commission confirms it completed that purchase on 3 August 2026, for $1.4 billion in cash plus up to $300 million in performance-linked payments.

Aquanow brings trading to the Visa work, Andy says, plus on-ramp and off-ramp, the steps that move money between regular currency and crypto. It also adds compliance and regulatory expertise to help Visa work through different corridors. He calls it a joint effort to serve Visa’s customers, using stablecoins to give them a better price and better speed on cross-border payment and settlement.

Visa announced the partnership in November 2025. According to Visa’s announcement, it expands Visa’s stablecoin settlement capabilities across Central and Eastern Europe, the Middle East and Africa (CEMEA). Visa’s network of card issuers and acquirers in the region can settle transactions using approved stablecoins such as USDC.

What convinced Visa? Andy points to track record. Aquanow’s trading infrastructure already met banking standards, which he says proved it could serve financial institutions, and years of work with banking clients built its reputation. For Visa, he says, that answered one checkpoint: does the technology meet the level they would expect?

The second checkpoint was that Aquanow is more than a technology vendor. Andy credits the company’s compliance and regulatory team with helping to explore how to open different corridors.

Announcement of a regulated AED-USD digital conversion framework in the UAE naming Universal, Mbank, AE Coin, Aquanow and Changer.ae
An announcement graphic on Aquanow’s website for a regulated AED-USD digital conversion framework in the UAE, with Aquanow among the named partners. Image: Aquanow (aquanow.com).

Getting licensed in the UAE, alongside the regulator

Ahmad notes that many companies chase licences, sometimes spending huge sums, and come away with nothing. He asks how Aquanow got its licence in the UAE.

When the UAE started drafting its virtual assets regulatory framework, Andy says, Aquanow was there and worked alongside the regulator. Seeing officials spend time talking to the industry gave the team confidence. “Without the proper regulatory framework, it is hard for financial institution to get into that space,” he says.

Aquanow was one of the early firms to get a brokerage licence, he says, and among the first few to talk to banks once it had it. Serving financial institutions had been the company’s goal from the start. Dubai’s Virtual Assets Regulatory Authority (VARA) gave Aquanow full operational approval in July 2024, according to the company’s announcement at the time. Its licence covers broker-dealer, lending and borrowing, and management and investment services.

Andy also welcomes competition. As the framework matures, more participants will come in, which he calls healthy for the market and a sign of confidence in the rules.

Why many countries are still unclear on crypto

Ahmad puts a common frustration to him. A founder from Canada, Singapore or India may want to build at home, but unclear rules push them to move to the UAE. What does Andy make of that?

He sees it as a matter of time. He points to the United States, which now has the GENIUS Act, a federal law for payment stablecoins signed in July 2025, and is working on wider regulation. In his view, there is no doubt the industry will mature, with more adoption and stronger frameworks across more countries. He names Turkey and Southeast Asia as places where a lot of work is in progress.

Now that some frameworks exist, Andy expects other jurisdictions to study them and set up their own, and more countries to have their own stablecoins. Regulators have a lot to think about, he says, but more institutional and business adoption is coming. “It is just a matter of time,” he says, for regulation to mature and for adoption to spread to more countries.

What still stands in the way of everyday use

Asked about a myth the industry still holds, Andy turns to mass adoption. Business adoption is rising, he says, because the infrastructure has become more mature, more robust and more reliable. That is the starting point.

The open question is retail. Bitcoin arrived in 2009, so why has everyday adoption not followed? Andy asks whether the cause is the user experience, the wallet, and “certain complexity in the crypto that’s still creating friction” for normal people.

His view is that adoption will come down from the business side first, built on real use cases that save time, save money and deliver faster. The next step is to bring retail users in as well, which he says would be good for the whole ecosystem.

He also sees growth in tokenization. Alongside stablecoins, he says, the market needs more investable products on-chain, and that work is under way.

What’s next for Aquanow: start with the client’s pain point

On future plans, Andy calls payments an interesting domain. With stablecoin payments covering many corridors, the company has to decide which markets to prioritise and enter first.

His method is to listen to clients. What do they need? Where are they from? Where is the pain point, and how does Aquanow’s solution fit it? The technology will keep improving, he says, but the use case comes from what clients need, and serving them well is the key.

Ahmad picks up on this at the end, saying many companies in the space miss this focus on customer feedback.

Advice for anyone building in this space

Andy’s first piece of advice is about pace. “The crypto world is still moving really fast,” he says. Anyone who wants to get into the industry should “pay attention to what’s happening in the regulatory side” and to developments in different jurisdictions, because regulation is what allows the industry to grow.

Technology keeps changing too. In payments, he lists orchestration, integration and partnerships as big questions, and some of these are not blockchain problems at all. The interesting work is bringing different pieces together and connecting them to a blockchain solution.

His last suggestion is for people outside crypto trading and payments: think about how blockchain technology could be used in your own industry. That, he says, is one way to help the whole sector grow.

Final thoughts

The interview offers a practical picture of how crypto reaches the mainstream: through banks and payment networks first, with the complexity hidden behind an API. Andy’s lesson is that this takes more than code. Aquanow’s path from a Canadian liquidity provider to a licensed, full-stack partner for banks and Visa rests as much on compliance and regulatory work as on technology.

Some of what he describes is on the public record: the Visa partnership, the VARA licence and Mastercard’s purchase of BVNK. Other points are forecasts, such as more countries building clear frameworks, more national stablecoins and retail adoption following business use. Treat those as one builder’s view of where the market is heading.

Watch the full conversation on the TBP Podcast YouTube channel.

Frequently Asked Questions

Q: What is Aquanow?

Aquanow is a B2B digital asset infrastructure company founded in Canada in 2018. It works behind banks and other financial institutions, handling crypto trading, onboarding, compliance, settlement and custody through an API.

Q: Who is Andy Leung?

Andy Leung is the CTO and co-founder of Aquanow. He came from bank capital markets, with experience in equities, fixed income and FX, and leads the company’s technology and platform development.

Q: What is the Visa and Aquanow partnership?

Announced in November 2025, the partnership expands Visa’s stablecoin settlement in Central and Eastern Europe, the Middle East and Africa. It lets Visa’s issuers and acquirers settle transactions in approved stablecoins such as USDC. Andy says Aquanow contributes trading, on-ramp and off-ramp services, and compliance expertise.

Q: How do stablecoin cross-border payments help banks?

Andy says stablecoins can give customers a better price and faster cross-border settlement. Banks using a provider like Aquanow do not need their own crypto team; they integrate an API while the provider handles wallets and compliance.

Q: Does Aquanow hold a licence in the UAE?

Yes. Dubai’s Virtual Assets Regulatory Authority (VARA) gave Aquanow full operational approval in July 2024, covering broker-dealer, lending and borrowing, and management and investment services. Andy says the company worked alongside the regulator while the framework was being drafted.

Q: What is holding back everyday crypto adoption?

Andy says business adoption is growing as infrastructure matures, but retail users still face friction from user experience, wallets and crypto complexity. He expects businesses to lead, with retail following. This is an industry view, not investment advice – digital assets, including stablecoins, carry risks.

When Does Crypto Become Just Finance? Wachsman’s David Answers

0
When Does Crypto Become Just Finance? Wachsman’s David Answers

In early 2014, David Wachsman thought Bitcoin was a scam. Two nights of arguing with the head of a New York Bitcoin exchange changed his mind. About a year later, he started what he describes as the first communications firm built for the Bitcoin industry. Twelve years on, his question is no longer whether crypto works. It is when crypto stops being a separate industry and becomes simply part of finance.

On the sidelines of Token2049 in Singapore, Mohammad Ahmad Khan, co-founder of The Blockopedia, sat down with David Wachsman, Founder and CEO of Wachsman and President of Hawkeye Digital, Inc., for the TBP Podcast. In an episode of just over 19 minutes, they covered David’s Bitcoin origin story, why facts matter so much in a volatile market, what Hawkeye Digital invests in, why founders cannot pay for earned media, and what mainstream finance still needs before crypto is “just finance”.

Key Takeaways

  • David Wachsman thought Bitcoin was a scam until a long debate with the CEO of New York exchange Coinsetter in 2014. About a year later, he founded Wachsman, which he calls the first communications firm focused on the Bitcoin industry.
  • He describes most crypto assets as “effectively digital bearer bonds”: once value moves, there are no take-backs. That makes credible facts essential.
  • He expects digital asset companies to start disclosing information like public companies, in a standard format.
  • Hawkeye Digital, where he is President, is a publicly traded private equity and merchant banking platform. It takes equity, not tokens, in revenue-generating companies.
  • His main message to founders: earned media cannot be bought or controlled. A company controls only what it says.
  • He says blockchain is “nowhere near fully adopted” in mainstream finance, and expects tokenized securities to be far more common by 2030 to 2032.

From “Bitcoin was a scam” to the first crypto communications firm

Everyone in crypto has a Bitcoin origin story, David says. His starts at a New York technology party in the early mobile era, full of founders launching iPad apps and small social networks.

One of the most interesting people there was the CEO of a Bitcoin exchange called Coinsetter. It was the beginning of 2014, and David thought Bitcoin was a scam. The two argued for hours. David kept trying to find a hole in how Bitcoin worked, because he did not believe digital money could possibly work.

It took that night and the next, but David lost the argument. “It turns out there were no holes. It turns out Bitcoin actually works. I was wrong,” David says. From then on, he was convinced this was the future.

Coinsetter was a New York Bitcoin exchange founded in 2012. Kraken acquired it in early 2016, according to Kraken’s own blog.

About a year after that debate, David started Wachsman as the first dedicated public relations and strategic communications firm for the industry. He says crypto tripled in 2016 and rose about 30 times in 2017, and that Wachsman was the largest firm of its kind in the world the whole time.

What twelve years in crypto communications looks like

Wachsman’s first office was on Wall Street. David says the firm has been in Europe since 2017 and Singapore since 2018, with offices in London and Geneva and a presence in Seoul and the UAE.

When new layer one blockchains arrived, David says, Wachsman helped launch them. The work started with three questions for founders: “What are they building? How is it differentiated? Why does it need to exist?”

He lists other chapters:

  • Layer two networks, when Ethereum and other protocols needed to scale.
  • Security tokens, when many still saw them as a bad idea, and the early trading and tokenization platforms that later became today’s securitizers.
  • Decentraland, which he calls one of the first projects to use what became NFT technology.
  • The rise of meme coins.

Today, he notes, the largest stock exchanges are adopting blockchain for clearance, settlement and trading.

Why facts matter in a “dangerous” industry

Ahmad asks how the industry should tell its story and educate newcomers. David starts with sources. “It’s essential to learn from credible people who are going to give you real facts when learning about this industry,” he says.

His reason is the asset itself. For the most part, he says, crypto deals in “effectively digital bearer bonds”. Real value moves across the internet, and there are no take-backs once it is transferred. Markets are volatile, and losses are common. “Millions of people have lost millions of dollars over the years in this industry. I’m one of them,” he says.

Information asymmetry and bad intel make it easy to be taken advantage of. So media companies, he says, must tell the facts and not cover things up. Companies carry the same duty.

He also makes a forecast. “We’re going to see digital asset companies behave more like public market companies,” he says. They will disclose in a standardised way, either because regulation requires it or because the industry enforces it on itself, like a self-regulatory organisation (SRO). The reason, in his words: “we’ve seen too many people hoodwinked.”

At Wachsman, he says, the team verifies its facts as far as it can, then works with credible reporters who check everything again before publication. “This is a dangerous industry in many ways. It’s also extraordinary. It’s the most remarkable opportunity set, as far as I’m concerned, on Earth,” he says.

What Hawkeye Digital does

David describes Hawkeye Digital as a “publicly traded private equity and merchant banking platform”. Even as a public company, it invests in companies that meet its criteria, often in digital assets, and helps guide them through a capital markets journey while providing services.

The key word is equity. “We love tokens, obviously. We love crypto. But we take equity positions in these companies, and that’s our intended strategy,” he says.

His timing argument is about the United States, where he says the SEC, the CFTC, the OCC and other regulators have become more innovation-friendly. He expects more capital formation and more crypto companies going public.

The company is new in its current form. According to a Business Wire release on OTC Markets, an investment group led by David took a controlling interest in Hawkeye Systems, Inc. in 2026 and named him President. It rebranded as Hawkeye Digital, Inc. in August 2026 and trades over the counter as HWKE.

David lists what Hawkeye looks for:

1. Product-market fit, with a real user base.

2. Revenue today, and preferably real profits.

3. A need for capital to grow, for example to buy licences, cross borders or enter new markets.

He calls Hawkeye sector-agnostic. Wallets, stablecoin infrastructure, tokenization platforms and payments firms could all fit. These are not venture-stage bets, he says, but closer to private equity deals. “The reality is there’s no private equity market in crypto, certainly not a well-developed one by any means,” he says, and Hawkeye aims to act as a substitute. He is also interested in roll-ups, where merging two companies makes them more valuable together.

He invites founders to email [email protected]. Because Hawkeye is listed, he adds, anyone can track its performance, and “we disclose everything.”

Why Token2049 matters to Wachsman

Wachsman has worked alongside Token2049 since its first edition in Hong Kong in 2018, David says. The series has since run in Dubai, Singapore and London.

“It’s the largest conference series for crypto in the world,” he says, praising its speakers, sponsors and organisation. He expected this year’s edition, with its side events, to sell out and fill effectively all of the Marina Bay Sands conference centre.

Readers should know the relationship behind those words. In an August 2026 announcement, Wachsman marked eight years as Token2049’s Agency of Record. The same release said the 2025 Singapore edition sold out with more than 25,000 attendees from over 7,000 companies.

Aerial night view of a city from the Locations page of the Wachsman website
An aerial city view from the Locations page of Wachsman’s website. Image: Wachsman (wachsman.com).

When does a technology grow up?

Wachsman began in Bitcoin and now works across finance, AI and other emerging technology. Ahmad asks when a technology stops being “emerging” and becomes mainstream.

David points to the calendar. Token2049 Singapore took place in October 2026, the same month as Bitcoin’s 18th anniversary. Satoshi Nakamoto published the Bitcoin white paper on 31 October 2008. “Bitcoin turns 18. So, Bitcoin is a full-fledged adult this month,” he says. “I don’t think Bitcoin’s emerging technology.”

David says Wachsman now also works with large social networks, credit card companies and banks, but still likes complex startups. “The more complicated, sophisticated the better,” he says. If something is hard to explain but can make a difference, “we want to be there”.

Earned media: you cannot pay for it

Ahmad asks what David wishes founders understood before walking into Wachsman. “I wish more founders knew that earned media, you can’t pay for. There’s no bribing. You can’t control it. Reporters are going to write whatever they’re going to write,” he says.

He sees this as healthy. As a proud American, he believes in the First Amendment: reporters may write what they want, as long as it is accurate.

That is not a free pass for the press. He says “we should hold reporters accountable for their inaccuracies or for misinformation they put out there”. But founders need to accept the limits. “What you can do is control what you say,” he says. Done right, that shapes what is eventually published. “Earned media is earned, and there’s no two ways about it.”

What has to happen before crypto is “just finance”?

The industry has spent years talking about adoption, with ETFs and new rules along the way. Ahmad asks what must happen before people stop saying “adoption” and simply call it finance.

David’s answer: not yet. “Blockchain technology is nowhere near fully adopted in mainstream finance, not yet,” he says. Tokenized securities are still hard to trade, and “there’s effectively no liquidity for almost any of them yet.”

His test is volume. When tokenized securities, and tokenized commodities beyond crypto, trade billions of dollars a day, he will say the industry is past the adoption curve. Until then, they are separate industries. “Crypto is a niche, it’s a large niche of overall finance,” he says. He expects the two to blend further, and says “it seems pretty imminent.”

Policy is the brake. David says the United States had no pro-innovation set of regulators until President Trump was re-elected, and change still takes time. He also points to the defeat of the CLARITY Act. That federal market-structure bill failed a Senate cloture vote on 15 September 2026, short of the 60 votes needed, according to analyses by DLA Piper and Hunton.

Without that law, David says, regulators have to write the rules themselves. Rules need time to take effect and comment periods for critics, including traditional banks that may not want to be replaced by digital asset firms. Still, by 2030 or 2032, he expects tokenized equities and securities of every type to be “a heck of a lot more omnipresent.”

His last word for Token2049 visitors

David’s closing advice is to come and learn. “Have an open mind, ask hard questions,” he says. Make sure what you hear is factual, and check it again later. A conference gives direct access to founders, executives and staff from across the world. “Get someone in person and ask them hard questions. They’re going to be thrilled to answer.”

Final thoughts

David Wachsman’s message is consistent: in a market where transfers are final and information is uneven, facts are the main protection. His view of earned media follows from the same idea. A founder shapes a story by being clear and accurate, not by paying for it.

Some of what he shared is fact, such as Wachsman’s 2015 founding and Hawkeye Digital’s 2026 relaunch. Other parts are forecasts: standardised disclosures, more crypto listings and common tokenized securities by 2030 to 2032. Those depend on rules still being written after the CLARITY Act stalled. Readers should also note that David leads a firm investing in crypto companies and an agency that represents Token2049.

Watch the full conversation on the TBP Podcast YouTube channel.

Frequently Asked Questions

Q: Who is David Wachsman and what does Wachsman do?

David Wachsman founded Wachsman, a public relations and strategic communications firm, in 2015 and is its CEO. He describes it as the first such firm dedicated to the Bitcoin industry. He is also President of Hawkeye Digital, Inc.

Q: What is Hawkeye Digital?

Hawkeye Digital, Inc. (OTC: HWKE) is a publicly traded private equity and merchant banking platform. It takes equity stakes in revenue-generating companies, often in digital assets, and supports them with capital and advice for growth, roll-ups and a possible move to the public markets.

Q: Can crypto companies pay for media coverage?

Not for earned media. David says earned media cannot be bought or controlled, and reporters will write what they choose as long as it is accurate. A company can only control what it says.

Q: When will crypto become part of mainstream finance?

David says blockchain is “nowhere near fully adopted” in mainstream finance. He would call it just finance once tokenized securities and commodities trade billions of dollars a day, and he expects that to look far closer by 2030 to 2032. This is a forecast that depends on regulation.

Q: What does “digital bearer bonds” mean in crypto?

David uses the phrase for how most crypto assets behave: once a transfer is made, there are no take-backs. That is why he stresses credible sources. This article is not investment advice. Crypto assets and listed shares are volatile and can lose value.

Why Are Global Payments Still So Hard? Anyflo’s Lola Oyelayo-Pearson Explains

0
Why Are Global Payments Still So Hard? Anyflo’s Lola Oyelayo-Pearson Explains

Stablecoins can move money around the world in seconds. Yet for most businesses, paying a supplier or contractor in another country is still slow, costly and hard to explain to an accountant. According to one founder, the problem is not the technology. It is the missing layer between blockchains and the way ordinary businesses work.

On the sidelines of Token2049 in Singapore, Mohammad Ahmad Khan, co-founder of The Blockopedia, sat down with Lola Oyelayo-Pearson, Founder and CEO of Anyflo, for the TBP Podcast. Lola spent nearly four years at Mysten Labs, the original contributor to the Sui blockchain, after roles at Shopify and Capital One. Over 18 minutes, they covered the three problems Anyflo wants to solve, where it stands today, why Anyflo uses Sui but stays multi-chain, security, and why so few women reach the core of the industry.

Key Takeaways

  • Anyflo is building payment rails that let everyday businesses move money across borders on stablecoin rails, with fiat in and fiat out if they want it.
  • Lola names three problems: slow and costly cross-border money, fiat-to-fiat transfers through a “stablecoin sandwich”, and receipts that accountants and regulators can follow.
  • Anyflo is not fully live. It is testing with design partners in payroll, retail and travel, and banking, and hopes to secure an EU payments licence in the new year.
  • Her main lesson for crypto builders: “token go up is not a business model”. Teams that do not understand fiat rails have high potential but limited reach.
  • Anyflo leans on Sui for zero-gas stablecoin transfers but stays multi-chain. In her words, it locks customers into an outcome, not a blockchain.
  • She says no founder can promise never to be hacked. Anyflo is audited and keeps each customer’s funds separate.

From an agency to Mysten Labs: the road to Anyflo

Lola says she has always been described as entrepreneurial. In every job, her approach was to work out the problem, then build what was needed to solve it. Before Shopify, she was at Capital One. Before that, she worked at another blockchain startup, and earlier she ran an agency that was later sold to Cognizant. According to Anyflo’s website, she led teams at Shopify Money and Capital One UK, and was GM of Commerce and Consumer Product at Mysten Labs.

The idea grew out of her time at Mysten Labs working on Sui. She met many companies that wanted to use stablecoins, but no supply chain existed to service them. “It’s one thing to have the L1 and the infrastructure,” she says. To make it real, it has to be plugged into everyday businesses.

She calls Anyflo the company she wishes she could have introduced to firms from her past roles, naming Red Bull, Adidas and Lyft (they are not Anyflo customers). This year, she says, she took the chance: “we are building the payment rails to bring stablecoins to everyday businesses.”

The three problems Anyflo solves for businesses

Individuals who use stablecoins, Lola says, are usually comfortable with a self-custody wallet, an exchange or a decentralised exchange (DEX). Businesses are different. “When you are a business, you have hundreds of interfaces,” she says. To move money between many customers, suppliers and partners, “self-custody doesn’t work. Exchanges don’t work.”

Businesses must also meet rules on sanctions and money laundering and know where money is going. So “even the idea of using a decentralised exchange is incredibly scary”, she says, before anyone mentions hacks.

What businesses need, she argues, is a supply chain that understands how they operate. Anyflo’s pitch is to be that layer, aimed at three problems:

1. Cross-border money. Doing it in fiat is expensive and slow. Anyflo lets businesses do it on stablecoin rails.

2. Fiat in, fiat out. Some businesses want stablecoin speed but do not want to hold stablecoins. Anyflo supports a “stablecoin sandwich”: the payment starts in fiat, crosses on stablecoin rails and ends in fiat.

3. Records an accountant can understand. Instead of links to a block explorer, the business gets a receipt showing who sent what to whom and the route the money took, which auditors or regulators can also check.

“Those three things, they sound really easy, they’re very, very hard if you’re a business today,” Lola says. Few firms can offer this to a global audience, she adds, “not just US via Stripe and Bridge”.

Where Anyflo stands today

Ahmad asks what changes early partners have seen. Lola is direct: no partners are transacting fully yet. Anyflo has customer design partners who represent the needs it is designing for, in three areas:

  • payroll
  • retail and travel
  • a modern banking-type solution

“Our model is an orchestrator,” she says. Each transaction generates an intent, Anyflo puts it out for bids, and a solver with a quote completes it. Testing with design partners and liquidity providers runs over the next three to four months.

In parallel, Anyflo is building its compliance posture and hopes to have an EU payments licence in the new year. She then expects a full launch, starting with payments between Europe and the African continent, then Asia.

The public record lines up. According to Anyflo’s press release on PR Newswire, the company emerged from stealth on 8 October 2026 at Sui Basecamp during Token2049 Singapore, after being incubated within Mysten Labs. It entered private alpha in October, with a beta planned for the first quarter of 2027. Pulse 2.0 reported that Mysten Labs invested $1 million and that Anyflo acqui-hired Native, a Bitcoin lending project on Sui that finished in the top five of 630 projects at Sui Overflow 2025.

“Token go up is not a business model”

Asked what her experience taught her, Lola makes a joke she says she means in good faith: “token go up is not a business model.” She calls it her biggest insight.

Very few people know how payments work, she says, pointing to India’s UPI as “a very, very sophisticated solution to a chronic problem” built on deep infrastructure. Her edge is that she understands that infrastructure. “When you understand how fiat rails work, and then you think about how do I connect fiat and stablecoin rails, you actually have a magic insight that very few people understand.”

Many blockchain teams have great cryptographers and developers, she says, but “unfortunately for them, they don’t know how fiat rails work”, or how to build a business model. “And so they have high potential, but limited reach.”

She does not overclaim. The proof, she says, will come when Anyflo starts scaling transactions. “We’re not naive about how difficult it’s going to be,” she adds. Compliance and regulation are areas Anyflo will not compromise on.

What changes for a business that uses Anyflo

Today, Lola says, a business offering cross-border payments is usually in one of two places. Either the service is expensive and “your customer feels like they have no choice”, or it is cheap and the business makes little profit for the effort.

The first change is a stablecoin sandwich that removes correspondent banking, settlement delays and other costs. At a baseline, she says, the business could raise its profitability and lower the cost to its users.

The second change is choice. Her example is payroll. Contractors hired overseas may have banking problems and would rather receive a stablecoin than local currency, which is hard for payroll companies to deliver.

“Give your customers a choice,” she says. With Anyflo, a business that offers rupees or dollars today could also offer stablecoin dollars, or stablecoin rupees if they exist in future, with the same effort. “We just make it a simple extra option for the business,” she says, and it gains either margin or customer value.

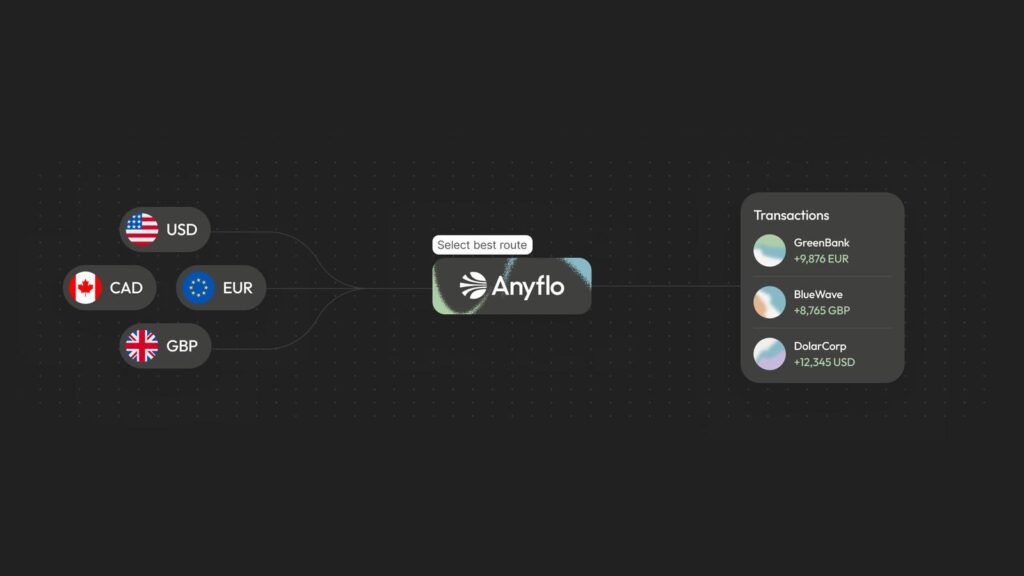
Anyflo routing concept: USD, CAD, EUR and GBP payments pass through one layer that selects the best route
Anyflo’s routing concept: payments in several currencies pass through one layer that selects the best route. Image: Anyflo (anyflo.io).

Will Anyflo get into cards?

Lola says many vendors on blockchain rails already specialise in stablecoin-backed card issuance, and Anyflo can tap that network. It will look at supporting “receive and spend”: an instant wallet, or a virtual bank account and an instant card.

The roadmap will follow customer demand. “We’re a small team, we’re agentically powered,” she says. Not every feature will exist on day one, but if a customer brings demand for cards, Anyflo will make it available.

Why Sui, and why Anyflo stays multi-chain

Given her Mysten Labs background, Ahmad asks what role Sui plays. Lola says Anyflo, as an independent orchestrator, can use any blockchain rails and has no fixed requirement to use Sui.

The practical case for Sui is cost. “The number one thing that Sui’s offering today that no other chain can match is zero gas on stablecoin transfers,” she says. “Taking gas out means that demand does not become a penalty on the business.” According to a Sui press release on PR Newswire, the network launched protocol-level gasless stablecoin transfers on 20 May 2026, taking fees for supported stablecoin transfers to zero. She also points to Sui’s native privacy features, which let Anyflo add services without extra vendors or cost.

If a customer needs a specific chain or asset, Anyflo will deliver it. If it only wants cheap, fast and reliable, she says Sui may be the right route nine times out of ten. “That’s the beauty of orchestrating,” she says. “I don’t lock you into one blockchain. I lock you into an outcome.”

Security: why no founder can promise never to be hacked

“I think it would be incredibly naive for any tech founder to say we will never be hacked,” Lola says. She adds that agentically powered development creates new risks as well as new benefits. She sets out what Anyflo does:

  • “We’re fully audited for our alpha right now,” she says, and audits will continue.
  • Engineering is led by Robert Zaremba, whom she describes as co-founder and CTO of Native, a Bitcoin collateralisation platform, and a developer who has worked with secure protocols on Near, Sui and EVM chains.
  • Anyflo builds security first, with regular testing and review on top.
  • Unlike an exchange, one customer’s money will not be mixed with other customers’ money or with Anyflo’s own.

That isolation keeps the damage surface very limited if something goes wrong, she says. Anyflo’s website FAQ adds that it is non-custodial, with funds held by regulated custody and banking partners in segregated accounts.

“You make best efforts, you follow best practices, and then you hope for the best. And then if something goes wrong, you react really well,” she says.

Why so few women reach the core of the industry

Ahmad’s last question is why so few women reach the core of the industry. Lola says she cannot give a reason. She can speak to her own career: leaders who invested in her, and “powerhouse women” she reported to who showed her what it is like to be a CEO.

That built her confidence. “I’m not doing this as a female, but I happen to be a female. I happen to be a mother. I happen to be a wife,” she says. “It’s not about having it all. It’s about just doing the thing that you’re most passionate about.”

She suggests society sometimes gives men more freedom to focus on their passion. With a rich network and strong female role models, starting with her mother, the only questions for her were the right idea, experience and plan. She believes those have come together with Anyflo. “So, we’re just getting on with the job.”

Final thoughts

The interview makes a practical case. Lola is not saying businesses should want stablecoins for their own sake. She is saying stablecoin rails only help if they come with what businesses already rely on: compliance, clear receipts and fiat at both ends.

Much of this is still a plan. Anyflo is in private alpha, no partners are transacting fully, and the EU licence and full launch are targets. Her points on cost savings and Sui’s lead are her own views. The real test, as she says, will come when Anyflo starts scaling transactions.

Watch the full conversation on the TBP Podcast YouTube channel.

Frequently Asked Questions

Q: What is Anyflo?

Anyflo is a stablecoin payments orchestration company led by founder and CEO Lola Oyelayo-Pearson. It offers businesses one API to send and receive cross-border payments in their preferred currency, settled on stablecoin rails. It was incubated within Mysten Labs and emerged from stealth in October 2026.

Q: What is a stablecoin sandwich?

A cross-border payment that starts in fiat, crosses the border as a stablecoin and ends in fiat, so neither side has to hold stablecoins.

Q: Is Anyflo live?

Not fully. Lola says Anyflo is testing with design partners and liquidity providers and hopes to secure an EU payments licence in the new year. Its press release says it entered private alpha in October 2026, with a beta planned for the first quarter of 2027.

Q: Does Anyflo only work on Sui?

No. Lola says Anyflo is a multi-chain orchestrator with no fixed requirement to use Sui. Sui’s zero-gas stablecoin transfers make it a frequent choice, but Anyflo will use other chains when a customer needs them.

Q: How does Anyflo approach security?

Lola says the alpha is fully audited and each customer’s funds are kept apart from other customers’ and from Anyflo’s own money. She says no founder can promise never to be hacked.

Q: Which payment corridors will Anyflo serve first?

Lola says Anyflo plans to start with Europe and the African continent, then expand to Asia. This is a company plan, not a launched service. This article is not financial advice; stablecoins carry risks, so check licensing and terms before moving money.

Built in Eight Weeks: Can Vibrez Make Shared Moments Last?

0
Built in Eight Weeks: Can Vibrez Make Shared Moments Last?

Think about the last time you watched a big match, a concert or a DJ set on your phone. You probably scrolled through the comments and watched the stream. But did it feel like you were in the room with other people? For Christophe Dhaisne, Head of Product at Vibrez, the honest answer for most people is no. That gap, he argues, is what a new kind of social network should close.

In Singapore during Token2049 week, which ran straight into the Formula 1 Singapore Grand Prix weekend, Amreen of The Blockopedia sat down with Christophe for the TBP Podcast at a Formula 1 event with big screens set up to watch the race. Introduced on camera simply as Chris, he used the short conversation to correct a common assumption about the company, explain what a “moment” means on Vibrez and walk through what the team built in eight weeks as an AI-native company. He also described a 20-supercar road trip from London to Ibiza, and set out what comes next: a map that invites people to discover moments, and profiles built around passions.

Key Takeaways

  • Vibrez is not an events or retreat company. Christophe describes it as “a new kind of social network” and a super app built around shared passions.
  • The core idea is the “moment”. People who share a passion connect around a live experience, relive it later and reconnect with everyone who took part once it ends.
  • The team built its current app in eight weeks. Christophe calls it a proof of concept and credits the fast progress to Vibrez being AI native.
  • The app already covers the basics of Instagram-style posting and Twitch-style live streaming, including profiles, follows, photo and video posts and live streams.
  • A road trip of 20 supercars from London to Ibiza was run as a moment on Vibrez. The company’s FAQ dates it to 30 September to 5 October 2026.
  • The next big job is navigation. Christophe wants to turn a mostly static map into one that invites users to discover moments, and to build profiles around passions.

Not an events company: what Vibrez says it is

Amreen opened by describing Vibrez as a company that organises and hosts events. It was an easy assumption, given that the interview took place at a Formula 1 event in Singapore.

Christophe began his answer with “a small correction”. Organising events and retreats, he said, is “not what Vibrez is all about.”

“Vibrez is a new kind of social network. And Vibrez is what you could call a super app,” he says.

In Christophe’s telling, real-world experiences such as a race weekend or a road trip are not the product itself. They happen inside the app, where people can watch, take part and stay connected afterwards. The company’s website frames this as one universe with three gates: nightlife, sports and events.

The problem: watching alone on a phone

Rather than describe the product straight away, Christophe turned the question back on the host. He asked her to think of the last time she watched a big game, a movie, a concert or a DJ set on her phone, and whether it felt like she was with other people in the room.

Amreen recalled watching a concert in Dubai during Global Village. When pressed, she said she was “just watching it.”

That was his point. When people watch something on a phone, he said, they scroll through comments and watch the video, “but you’re not participating with other people, right? You’re not engaging with other people.”

Christophe says this is the problem at the core of what Vibrez is solving. In his view, today’s platforms show content to large audiences but do not make a viewer feel part of a group sharing the same experience, or keep that group together once the event is over.

What is a “moment” on Vibrez?

The answer Vibrez offers is built around one word: moments.

“Vibrez is a place where people who share the same passion can get connected, can engage through moments,” Christophe says. He then describes three stages. First, you live the moment. Then you can relive it. Finally, “you can make it last.”

The third stage is the one he stresses most. “Once the moment is over, you can reconnect with all the people you shared this moment with,” he says.

A moment can take many forms. Christophe says a content creator “can create different types of moments, a party, a road trip if you want to, anything,” and use those moments to engage a community. The app’s App Store listing describes the same idea in product terms. Users can create Live Streams, Parties and Roadtrips inside buildings on the Vibrez map, and join live video, audio, chat and reactions.

He is confident about how new this is. “As a social platform, there is no equivalent to what we’re actually building today,” he says. That is the company’s own view.

What was built in eight weeks

Amreen asked Christophe to walk her through the app as if she had just downloaded it. Where does a new user land, and what makes the room come alive?

His first answer was a reality check. In his book, what the team has built in eight weeks is not yet even a beta or an alpha version. “It’s pretty much a proof of concept,” he says.

What makes the speed possible, he says, is the way the company works. “Since we’re AI native, the development is going extremely fast.”

In those eight weeks, Christophe says the team has put in place core features that users would recognise from Instagram and Twitch:

  • creating a profile
  • following and unfollowing people
  • posting all types of content, including video and pictures
  • live streaming, which he compares to “what you would do on Twitch”

He sums it up as having built “the core functionality of a social network like Instagram, which is pretty impressive.”

The company’s public pages reflect that pace. The Vibrez FAQ says the team ships “faster than the stores can review,” with most updates reaching users over the air while the app is running. The App Store listing also describes a feed called Pulse for text, photo and video posts, direct messages and community games.

London to Ibiza: a supercar road trip as a moment

To show what a moment looks like in practice, Christophe pointed to an event the team had organised the week before the interview.

“20 supercars left London all the way to Ibiza with different stops all the way through,” he says. “And this road trip is actually a moment on Vibrez.”

The Vibrez FAQ confirms the dates. Roadtrip 2026 ran from London to Ibiza from 30 September to 5 October, and users can relive it in the app. The FAQ adds that the Roadtrip feature can ask for a user’s location to guide them to the next checkpoint, and that this is optional.

A road trip is a clear first example of the idea: a start, a finish, stops along the way and a group of people who share one interest, in this case supercars.

Vibrez app on a phone showing its universe as a map of districts and buildings
The Vibrez app presents its universe as a map of districts and buildings. Image: Vibrez (vibrez.com).

Who is behind Vibrez?

According to its website, Vibrez is run by Vibrez Universe Pte. Ltd., a company registered in Singapore. Its privacy policy lists an office at Millenia Tower in Singapore and says the service is only for adults aged 18 and over.

Vibrez is a portfolio company of La Royale Group, a privately held investment group headquartered in Singapore and led by Group CEO Madelynn Loo. In a press release carried by Markets Insider, La Royale described Vibrez as a Singapore-based startup “developing a digital entertainment platform connecting music, sports and fan communities,” and said the app was in beta.

In a LinkedIn post, La Royale Group also said Vibrez used race week in Singapore to introduce the app to real users and gather feedback ahead of its beta launch. That fits Christophe’s description of a product still at the proof-of-concept stage.

The timing also explains the setting of this interview. Token2049 Singapore took place at Marina Bay Sands on 7 and 8 October 2026, with 25,000 attendees from 160 countries set to attend, according to a TOKEN2049 press release. The Formula 1 Singapore Grand Prix followed on the weekend of 9 to 11 October. Vibrez is not presented as a crypto project, and Christophe did not mention tokens or blockchain at any point in the conversation.

The hard part: rethinking navigation and the map

Amreen asked what the next city or moment for Vibrez would be. Christophe answered by describing the product work ahead.

Development is moving fast, he said, and the team is “adding functionalities on the go.” He admitted there is still a gap to close with the posting features people know from Instagram. “But that’s easy to do, without being cocky,” he says.

The bigger challenge, in his view, lies elsewhere. “I think the challenge today is really to rethink the navigation, how people navigate through this virtual world,” he says.

Vibrez presents its universe as a map. On the App Store, the company describes browsing districts and buildings to discover communities and join what is happening inside them. Christophe says that map is “pretty much static” today.

The goal is to change that. “We want the map to really invite you to discover moments through the different people and the artists and all the content creators which you will follow on Vibrez,” he says. He accepts the team still has “a bit of work to do” on this side.

Profiles built around passions

The second area of change is the profile.

Until recently, Christophe says, the Vibrez profile was mostly a way to write a small bio. The team has now added a new function. “Today you can already share your passions and indicate what passions you’re into through your profile and find people who share the same passions as you on the app,” he says.

That links back to the company’s tagline, “Share the Passion”, and to its core idea that people should connect through shared interests rather than a general feed. Recent App Store release notes describe the same update, inviting users to “tell us your passions and meet members who share them,” alongside a longer 500-character bio.

What comes next for Vibrez

Christophe closed with a simple message. “This is just the beginning. Stay tuned because the app is going to evolve very rapidly in the coming days and weeks.”

The company’s own pages give some clues about what is on the way. The Vibrez homepage says the Nightlife and Sports gates are open, while the Events gate, covering concerts, festivals and the pit, opens next. Its Moments page lists upcoming moments for Singapore, the Road to Ibiza, Ibiza and a Solomun Closing 2026 event, all marked “coming soon”.

Final thoughts

The interview is short, but it makes one argument clearly. Christophe believes that watching on a phone has become a solitary habit, and that a social network built around shared moments can turn it back into a group experience that lasts after the event ends. The supercar road trip from London to Ibiza is the first public example of that idea in action.

It is worth separating what exists from what is planned. Profiles, follows, photo and video posts, live streaming and passion tags are features Christophe says are live today. A map that actively invites users into moments, and an Events gate for concerts and festivals, are still on the roadmap. His claim that no equivalent platform exists is the company’s own view, and the app remains, by his own description, a proof of concept built in eight weeks.

Watch the full conversation on the TBP Podcast YouTube channel.

Frequently Asked Questions

Q: What is Vibrez?

Vibrez is a social app from Singapore-registered Vibrez Universe Pte. Ltd. Its Head of Product, Christophe Dhaisne, describes it as “a new kind of social network” and a super app where people who share a passion connect through live moments, relive them and reconnect afterwards. The app is for users aged 18 and over.

Q: What is a “moment” on Vibrez?

A moment is a shared experience inside the app, such as a party, a live stream or a road trip. Creators use moments to engage their community. Once a moment ends, people can reconnect with the others who took part in it.

Q: How long did it take to build the Vibrez app?

Christophe says the team built the current version in eight weeks. He calls it a proof of concept and says the fast progress comes from Vibrez being an AI-native company.

Q: What features does Vibrez have today?

According to Christophe, users can create a profile, follow people, post photos and videos, live stream and list their passions to find like-minded people. The App Store listing also mentions direct messages and a map of districts and buildings.

Q: What was the Vibrez London to Ibiza road trip?

It was a road trip of 20 supercars from London to Ibiza with stops along the way, run as a moment on Vibrez. The company’s FAQ says Roadtrip 2026 ran from 30 September to 5 October 2026.

Q: Is Vibrez a crypto or blockchain project?

Nothing in the interview or on the company pages we reviewed describes Vibrez as a crypto or blockchain project. The conversation was recorded in Singapore during Token2049 week, but it focused only on Vibrez as a social and entertainment app.

Will AI Agents Become Finance’s New Interface? OKX’s Lennix Explains

0
Will AI Agents Become Finance’s New Interface? OKX’s Lennix Explains

For more than a decade, crypto exchanges have competed on the screen. Faster apps, cleaner charts, fewer taps to place a trade. According to one of OKX’s longest-serving executives, that contest is about to change. The next big user of a crypto exchange may not be a person at all – it may be a fleet of AI agents acting on that person’s behalf.

On the sidelines of Token2049 in Singapore, Mohammad Ahmad Khan, co-founder of The Blockopedia, sat down with Lennix Lai of OKX for the TBP Podcast. Lennix joined OKX in 2017 after a career in traditional finance. Over 18 minutes, the conversation covered why he left Wall Street for a young exchange, why AI agents in crypto trading are now an infrastructure priority, how exchanges are turning into financial super apps, and why so many crypto exchanges did not survive the last bear market.

Key Takeaways

  • OKX believes AI will become the next trading interface. Users may stop clicking through apps and instead direct agents that trade, pay and manage wealth for them.
  • Being “agent ready” means more than an API. It needs secure servers, permission rules for what an agent can and cannot do, updated compliance standards and the capacity to handle agent-scale traffic.
  • Lennix does not call OKX an operating system for crypto. He calls it an “agentic layer” that lets ordinary users talk to financial products in plain language.
  • Within five years, he expects crypto exchanges to become financial super apps that hold equities, forex, commodities, rates products and crypto in one margin account, trading 24/7.
  • Exchanges that depended only on crypto trading volume were wiped out in bear markets. Survivors widened into traditional finance products, banking partnerships and audits.
  • His advice to newcomers to this cycle: the stories are stablecoins and real-world assets (RWA), so study the companies building them, not only the tokens.

From Wall Street to a young crypto exchange

Lennix joined OKX in 2017, more than eight years ago. At about the same time, he read the Bitcoin white paper for the first time. He admits that before that, he thought Bitcoin was a scam. The paper changed his mind. It is only a few pages long, and he was struck by how simple the mathematics behind it was.

He came from a traditional banking and trading background, with past roles at JP Morgan and AIG. Those firms were sophisticated and ran huge operations. OKX, by contrast, was very young. His first job there was to bring traditional financial products into crypto.

The reason was volatility. Bitcoin’s annualised volatility at the time ran above 100%. Lai’s view was that more financial instruments and derivative products would help smooth the market, improve liquidity and give traders better tools for managing risk.

Why you cannot copy traditional finance one-to-one

The early plan was to take what worked in traditional markets – funds, ETFs, index products – and rebuild them for crypto. It did not work. Crypto, Lennix says, is a very different market, and you cannot replicate traditional finance 100% in one go.

His example is collateral. Eight years ago, USDT was not yet the default stablecoin for trading. If you wanted to trade a Bitcoin derivative, the only thing you could deposit was crypto itself, usually Bitcoin or Ethereum. That meant traders were buying Bitcoin derivatives with Bitcoin as margin. The profit-and-loss curve of such a position is not linear, so OKX had to make many adjustments in its back end.

The textbook concepts stayed the same. The details changed. Lennix calls those small adjustments innovation: tailoring proven instruments to the special conditions of the crypto market.

OKX in one line: the glue between two worlds

Asked to describe OKX in a single line, Lennix answers that it sits in the transaction between traditional finance and crypto finance. “We are the glue of these two worlds,” he says, describing OKX as a global fintech powerhouse.

That positioning has hard numbers behind it. In March 2026, Intercontinental Exchange (ICE), the parent company of the New York Stock Exchange, took a stake in OKX at a $25 billion valuation and a seat on its board, with plans to give OKX’s roughly 120 million users access to ICE’s U.S. futures markets and tokenized NYSE-linked equities.

Why a crypto exchange cares about AI agents

This is the core of the interview, and the reason the episode is titled “Will AI Become Finance’s New Interface?”

Lennix says OKX believes AI is likely to become the next-generation trading interface – the way people interact with the whole financial ecosystem. Until now, fintech companies, banks, neobanks, crypto exchanges and wallets have spent huge effort on UI and UX. Every product was built to serve a human.

Once AI becomes powerful enough, and intelligence becomes scalable and cheap, that changes. People may no longer interact directly with an exchange’s products. Instead, they will use a fleet of agents, each acting like a specialist, that interact with the exchange for them.

So OKX is planning for a new kind of customer base. It serves tens of millions of human users today, but it may need to serve billions of agents tomorrow.

What “agent ready” means in practice

Lennix lists what an exchange must upgrade before agents can safely use it:

  • API services and MCP servers – machine-friendly ways for agents to read data and place orders.
  • A security layer – so an agent can sign approved transactions without ever touching a user’s private keys.
  • Security policies and a permissions framework – clear rules on what an agent can and cannot do.
  • Upgraded authority and compliance standards – built for agent activity, not only human accounts.
  • Capacity for agent-scale traffic – the ability to handle billions of agent transactions.

These are not only ideas on a podcast. OKX has already shipped parts of this stack. Its open-source Agent Trade Kit lets AI assistants trade on OKX through the Model Context Protocol, with API keys kept locally and options such as a read-only mode and rate limits. In mid-2026, OKX also opened OKX AI, a marketplace where agents hire each other and settle payments in stablecoins, after a closed beta with 50 early AI service providers.

OKX AI marketplace where AI agents find work and settle payments in stablecoins
OKX AI, the company’s marketplace where AI agents find work and settle payments in stablecoins. Image: OKX (okx.ai).

Is OKX building the operating system of crypto?

Ahmad asks whether OKX wants to become the “on-chain AI OS” – a base layer that apps and agents build on. Lennix pushes back on the label. It is hard to call it an operating system, he says. He prefers “agentic layer”, or an agent-ready layer that others build on.

He breaks an agent down into the parts a platform must support:

  • the ability to work with a large language model
  • a way to define the gateway and the boundaries of each agent
  • a way to review, step by step, what an agent has and has not done
  • a way to evaluate how effective your agents are
  • a basic security layer, so agents can only sign authorised transactions without access to private keys

The goal, he says, is to let ordinary users talk to OKX’s products in plain language, with agents doing the work in between.

Crypto exchange vs brokerage: what changes in five years

Crypto exchanges now list stocks and ETFs. Will people still see a difference between a crypto exchange and a normal brokerage in five years? Lennix says yes – by principle, they will remain very different.

His prediction is that crypto exchanges will become financial super apps. One app would hold equities, forex, commodities, interest rate swaps, structured products and crypto. All of it would sit in one collateral and margin account, with one buying power and one equity balance. It would be regulated, and it would trade 24 hours a day, seven days a week.

Brokerages may evolve and add products too. But Lennix argues an exchange like OKX already does more than a trading platform does. Beyond the brokerage-style front end, OKX is:

  • a wallet operator
  • a blockchain layer developer
  • a card and payments provider for everyday spending

He sees the full journey – spending, wealth management with AI agents, trading, speculation, quantitative and high-frequency trading – living on one platform.

What Token2049 showed about the industry

Asked what people at Token2049 are underestimating, Lennix points to who was in the room. He saw many more payment firms, security tokenization firms and even cloud providers. In other words, a crypto conference full of traditional fintech players.

His reading is that crypto has become one part of a broader, holistic financial system. The industry is wider and bigger than before. People are realising the technology is neutral but useful to other asset classes too. The experience of running a crypto company also applies to running businesses in other financial instruments. The result, he says, is that everyone is starting to build a single financial app that holds every kind of instrument.

Why so many crypto exchanges were wiped out

Many exchanges have disappeared from the market. Lennix says the reason is obvious. If your business is purely a crypto exchange – spot and derivatives, trading only – your revenue depends on crypto volatility, mostly Bitcoin’s. When the crypto market has a bad time, that business model is very hard to sustain.

Two forces are now reshaping the field:

  • Fintechs are moving in. Clearer regulation is the main reason. More governments now have clear definitions of crypto, rules on how it is regulated and licences firms can apply for. A stable payments company, wallet or bank can use that clarity to extend its products and audience into crypto.
  • Big crypto players are moving out – into traditional finance. Larger exchanges like OKX now offer traditional products, work with banks, are audited by Big Four firms, and collaborate with institutions such as BlackRock. They also build their own wallets and settlement layers, such as X Layer.

The wider product range makes these firms much less sensitive to a crypto winter. Lennix expects many crypto-only firms to fall away, while new players expand into the crypto audience.

Advice for people entering crypto this cycle

Lennix says this cycle has fewer narratives than the last. Past cycles were driven by memecoins, DeFi, yield optimisation and similar themes. This one is mostly about stablecoins and real-world assets (RWA), and how RWA interacts with the rest of the market.

That shifts what matters. Underlying technology and scalability are still important, he says, but the focus now is the link between traditional finance and crypto. His advice: do not look only at Bitcoin. Put much more weight on the future of the crypto companies themselves, not only their tokens.

What’s next for OKX

On future plans, Lennix names three priorities:

  • More traditional finance products – adding equities in different regions and more commodities on a tokenized platform.
  • The ICE collaboration – which would give OKX the ability to offer true one-to-one tokenization of underlying shares, integrated into the OKX product suite. ICE and OKX expanded this in June 2026 through a joint venture for tokenized equities.
  • AI across the roadmap – AI is now a central part of OKX’s product strategy. The aim is a next version of its AI products, so users can trade with AI easily and seamlessly.

Final thoughts

The interview makes one argument clearly: the exchange of the future is less a trading screen and more an infrastructure layer. If Lennix is right, the winners will be platforms that are safe for agents to use, broad enough to survive a crypto winter, and regulated enough to sit alongside traditional finance.

It is still a forecast. Agent-driven trading raises open questions on security, liability and regulation, and much of it is at an early stage. Anyone letting an AI agent act on their funds should start with read-only access, small limits and a clear view of the risks.

Watch the full conversation on the TBP Podcast YouTube channel.

Frequently Asked Questions

Q: What are AI agents in crypto trading?

AI agents are software programs, usually built on large language models, that act for a user. In crypto trading they can read market data, place orders, manage positions or make payments within limits the user sets. OKX expects users to direct fleets of such agents instead of using exchange apps directly.

Q: What does “agent ready” mean for a crypto exchange?

According to OKX’s Lennix Lai, it means offering APIs and MCP servers for agents, a security layer that lets agents sign approved transactions without touching private keys, permission rules, upgraded compliance standards and the capacity for very high agent traffic.

Q: Is OKX building an operating system for crypto?

Lennix does not use that term. He describes OKX as an “agentic layer” – infrastructure that lets developers build agents and lets ordinary users interact with OKX products in plain language.

Q: Will crypto exchanges replace brokerages?

Lennix says the two will remain different. He expects crypto exchanges to become financial super apps with equities, forex, commodities, rates products and crypto in one margin account, trading 24/7, plus wallets, payments and blockchain infrastructure.

Q: Why did so many crypto exchanges shut down?

Exchanges that relied only on crypto trading earned most of their revenue from crypto volatility. In bear markets that revenue collapses. Firms that broadened into traditional finance products, banking partnerships and audits became less exposed to crypto winters.

Q: What should new crypto investors focus on this cycle?

Lennix says this cycle centres on stablecoins and real-world assets. He advises newcomers to study the companies building in crypto, not only the tokens. This is an industry view, not investment advice – crypto assets are volatile and can lose value.

Bitcoin and Ethereum Are Planning for Quantum Computers. Q-AMCHAIN Started There

0
Bitcoin and Ethereum Are Planning for Quantum Computers. Q-AMCHAIN Started There

For most of the past decade, the quantum threat to cryptocurrency sat in the “someday” column. This year it moved closer.

On March 31, Google’s Quantum AI team published a 57-page paper estimating that the elliptic-curve cryptography (ECC) behind Bitcoin and Ethereum wallets could be broken with fewer than 500,000 physical qubits, in a runtime measured in minutes rather than days. Earlier estimates ran into the millions. Ethereum researcher Justin Drake and Stanford cryptographer Dan Boneh were among the co-authors. A week before, Google had set the end of 2029 as its own deadline for moving its products to post-quantum cryptography (PQC).

No quantum computer that size exists yet. But the gap between theory and hardware keeps narrowing, and public blockchains are notoriously slow to change.

Timeline of post-quantum cryptography deadlines for blockchains from 2024 to 2035
Key dates in the move to post-quantum cryptography, from NIST’s first standards to the deadlines now being set by governments and companies.

How the Biggest Networks Are Responding

Bitcoin’s leading proposal is BIP-360, written by developers Hunter Beast and Ethan Heilman. It was merged into Bitcoin’s improvement proposal repository in February as a draft. It defines a new output type, Pay-to-Merkle-Root, which drops the Taproot key-path spend that leaves a public key visible on-chain. It also lays the groundwork for post-quantum signature schemes to be added later through separate soft forks. A merge is not an endorsement, and no activation date has been agreed.

Q-Fortress post-quantum encrypted data storage by Q-AMCHAIN

Ethereum has moved faster on organisation. In January, the Ethereum Foundation formed a dedicated post-quantum security team led by Thomas Coratger, and Drake said the foundation had declared PQ security a “top strategic priority”. Its public roadmap says upgrades to the base protocol could be completed by 2029, with the full move of user accounts taking years longer. The quantum-resistant algorithms under evaluation include Falcon, Dilithium and SPHINCS+.

Why Retrofitting Is Hard

Upgrading a live blockchain is nothing like patching a server. Every holder has to move funds to new addresses, and coins whose owners have lost their keys cannot move at all. That has opened an uncomfortable debate among Bitcoin developers. A second draft, BIP-361, co-written by Jameson Lopp, would eventually freeze coins that are not moved to quantum-resistant addresses. Critics call that confiscation, while Lopp has said he wrote it because he dislikes the alternative even more.

Size is another problem. Post-quantum digital signatures are much larger than today’s, which puts pressure on block space and fees.

Starting From the Other End

Q-AMCHAIN, a blockchain developed by Ameritec IPS of Irving, Texas, takes the opposite route. Rather than adding quantum resistance to an existing network, it uses lattice-based post-quantum cryptography for identity, signatures and encryption as part of its base design. Lattice-based schemes are the family behind ML-KEM and ML-DSA, two of the three PQC standards NIST finalised in August 2024.

Its consensus layer, Forest Protocol, is described as a leaderless, staked DAG. The project’s technology page also mentions “hybrid compatibility strategies” for phased migration, an acknowledgement that a new chain still has to connect with older systems. In October, CertiK published its audit of the chain’s code, which lists 79 findings across 145 files. All but one were resolved, including the five rated critical.

The Trade-Off

A clean start has obvious appeal. There are no legacy addresses with exposed public keys and no dormant coins to argue over. But a new network also lacks what Bitcoin and Ethereum have spent years building: liquidity, large developer communities and a long record of surviving attacks. Q-AMCHAIN’s performance claims, up to 30,000 transactions per second in optimised benchmark conditions, have yet to be tested at public scale.

Q-AMCHAIN quantum resistant blockchain network

The two approaches may meet somewhere in the middle. The large networks will keep upgrading in stages, while newer chains try to prove that quantum-resistant design works in practice. NIST’s draft transition guidance proposes that quantum-vulnerable algorithms such as RSA and ECC be deprecated after 2030 and disallowed after 2035. Whichever route a network takes, it is now working against roughly the same clock.

Q-AMCHAIN’s design is outlined on its technology page, and its developer, Ameritec IPS, also builds post-quantum storage and biometric identity products.

In Studio, Not On Stage: When Shift Happens’ Kevin Follonier on Why He Never Networks

0
In Studio, Not On Stage: When Shift Happens’ Kevin Follonier on Why He Never Networks

The Blockopedia caught up with Kevin Follonier, founder of When Shift Happens, in person at Bitcoin Asia 2026 in Hong Kong, just a day after Kevin sat down with CZ for an interview on the conference’s main stage. The Blockopedia’s Co-founder Mohammad Ahmad Khan sat with Kevin to talk about how a media company built almost entirely without conferences, networking or a marketing budget ended up landing Saylor, Brian Armstrong, and CZ.

Kevin’s path into crypto started with an exit. After building and selling a data analytics company in London between 2015 and 2018, he went looking for a depressed market to put his money into, and found one: crypto in late 2018. He went all-in on Bitcoin and ETH in early 2019, then lost nearly everything trading leverage on BitMEX during the March 2020 COVID crash. He rebuilt through the 2020 and 2021 bull run, only to lose 92 percent of it again, roughly seven or eight million dollars in two days, when Terra Luna collapsed. Somewhere in the wreckage of that cycle, sitting through the FTX fallout and a media landscape he found genuinely bad, the idea for When Shift Happens took shape: studio quality, long form interviews with the industry’s biggest founders, built to make crypto look serious rather than chaotic.

Ahmad opened by half joking that he felt a little intimidated sitting across from someone who had been with CZ just a day earlier. Kevin waved it off immediately, telling him not to worry, that he was just a normal guy, no different from anyone else in the room. It set the tone for the rest of the conversation, which stayed loose and direct rather than the usual polished exchange between two crypto media figures.

Meeting CZ Was the Payoff of Three and a Half Years of Compounding

Kevin was candid that Tuesday’s on stage conversation with CZ was his first time ever meeting him, and that it happened because CZ’s own team specifically requested Kevin as the interviewer for Bitcoin Asia. He traced that directly back to a two and a half hour interview with Michael Saylor recorded three months earlier, a conversation that reportedly drew interest from people connected to the Trump family wanting to appear on the podcast next. Sponsors including Bitwise, Jupiter, Athena, Kaito and Variational have all approached When Shift Happens directly, unprompted, something Kevin credits entirely to founders watching the podcast and immediately noticing how different it felt from a typical Zoom recorded crypto interview.

The Real Interview Already Happened, Off Stage

Kevin revealed something most of the room in Hong Kong didn’t know: he and CZ had already recorded a full studio podcast before the stage conversation even happened. In his view, that studio recording will end up mattering far more than the thirty minute stage appearance, simply because studio conversations allow for depth, intimacy and genuine connection that an on stage format never can. His prep process before any major interview runs into the double digits of hours, researching, talking to teams, and using AI tools to sharpen his questions down to the one or two that actually matter, all in service of avoiding what he called the industry’s most common failure mode: a shallow conversation about token price with someone who deserves better questions.

He Has Never Once Networked at a Conference

Perhaps Kevin’s most pointed claim was this: in over three years of building the podcast, he has never attended a side event and rarely sets foot in a main conference hall. His logic borrows directly from Naval Ravikant, that a genuinely good product pulls people toward it rather than requiring its creator to chase connections. For Kevin, the podcast itself functions as marketing, personal branding, business development and networking simultaneously, and a well produced episode reaches far more people than any stage panel ever could. He pointed to his Saylor interview’s 1.7 million views as proof that studio work outperforms conference visibility by an order of magnitude.

Ahmad pushed back gently here, noting that he himself had built a chunk of his own network through conferences and speaker slots, and asked whether that approach was simply wrong. Kevin didn’t dismiss it outright, but held his ground, saying the podcast format let him skip that entire game because the product did the networking for him instead.

Consistency Is the Entire Moat

Asked what separates him from the wave of founders and creators who start podcasts and quietly abandon them within weeks, Kevin’s answer was blunt: almost nobody actually sticks with it. He estimated that posting more than three episodes puts a creator in the top 10 percent of people who attempt podcasting, and posting more than twenty one puts them in the top 1 percent, a bar he considers absurdly low given how much opportunity sits on the other side of it. His advice to anyone starting out was to try many things without waiting for permission or trends to validate the choice, and to pay attention to which pursuit still feels compelling at inconvenient hours, alone, with no audience watching yet.

What’s Next

Kevin said he has deliberately turned down opportunities to expand into adjacent business lines, choosing instead to keep doubling down on the podcast itself rather than diluting focus. Being in the room with major founders early, he noted, has already paid off in ways beyond media, citing early conviction in Zcash and participating in Hyperliquid’s token generation event as direct results of relationships built through the show.

Ahmad closed by telling Kevin he hoped to sit down with him again for a longer conversation somewhere down the line, a sentiment Kevin returned warmly before the two wrapped up on the sidelines of the conference floor.


Watch the full conversation: https://www.youtube.com/watch?v=T44G1biLUE0 

LBank’s Kaia Wong on Why Culture, Not Just Listings, Is Becoming an Exchange’s Real Moat

0
LBank’s Kaia Wong on Why Culture, Not Just Listings, Is Becoming an Exchange’s Real Moat

In this episode of The Blockopedia podcast, LBank VP of Marketing and Partnerships Kaia Wong sat down with The Blockopedia co founder Mohammad Ahmad Khan to talk about scaling a global exchange to 55 million users across 210 countries, why LBank partnered with Pudgy Penguins and Nobody Sausage, and what actually separates an early listing from a reckless one.

Kaia‘s path into crypto started during her studies in London, where an early curiosity about Bitcoin led her and a group of partners into global expansion, growth and fundraising work after graduation. That work put her in the room for one of crypto’s largest raises, Telegram Open Network’s roughly two billion dollar fundraising effort, which is where she first connected with LBank. Nearly five years later, she has helped grow the exchange more than tenfold, shifting her own focus increasingly toward VIP ecosystem partnerships and commercial strategy as she came to see users and partners as an exchange’s most valuable asset.

Three Things LBank Leans On

Asked what separates LBank in an increasingly crowded exchange landscape, Kaia pointed to three pillars: early access to credible new assets before they are fully priced in, genuine liquidity depth in smaller and newer tokens rather than just the usual BTC and ETH pairs everyone already offers, and a brand culture she described as more open and vibrant than most competitors, something the Pudgy Penguins and Nobody Sausage partnerships have only reinforced.

Going Global Without a Copy Paste Playbook

Scaling into 210 plus countries taught the team that global growth cannot follow a single template. Trading habits, product preferences, and even how users build trust in a platform vary significantly by market, which means localization has to go far deeper than translation, extending into product priorities, support models and campaign design shaped by close relationships with local partners.

What Actually Gets a Token Listed

Kaia broke down LBank’s vetting process into three layers: project quality, including team credibility and verifiable token economics; real market data like genuine user activity, capital flow and holder distribution; and timing, since even a strong project can be wrong for the market at a given moment. Her line for distinguishing early from reckless was direct: early is when data leads, reckless is when hype leads, and delisting happens quickly if a listed project starts showing signs of harming users.

Why Culture Became a Strategic Bet

With trading products across exchanges converging, Kaia argued that culture is what builds loyalty beyond the trade itself. Pudgy Penguins brings warmth and belonging, Nobody Sausage brings humor and creativity, and together they signal a younger, more human side of LBank’s brand. She was careful to draw a line, though: these partnerships don’t turn LBank into an entertainment brand, security and asset integrity remain the foundation, culture just gives users a reason to stay.

On avoiding the trap of sponsorships feeling like empty logo placements, Kaia said LBank is selective about partners specifically because forced fits are obvious to users immediately, and the bar is whether a partnership creates real value for a community rather than simply borrowing its attention.

Stocks, Security and the Bigger Picture

LBank’s push into US equity linked products and pre-IPO access, spanning more than 300 stock and ETF offerings accessible through a single USDT balance, reflects what Kaia called a broader opening of global liquidity rather than a simple grab at TradFi’s existing market. On security, following a string of high profile industry failures, she pointed to LBank’s multi layer security architecture, ISO IEC certification, and a newly established 100 million dollar futures risk protection fund, summarizing the philosophy simply: no trust, no trade.

Where She Sees the Next Wave Coming From

Rather than betting on any single narrative, Kaia expects the next phase of adoption to come from real world assets, application layer products and AI converging in practical, user facing ways rather than existing as separate hype cycles.

Rapid Fire

Asked to choose in a word, Kaia picked futures over spot for where the real action is right now, said LBank is building primarily for Web3 native users looking to cross into TradFi, called bear markets the real proving ground for brand trust, and ultimately described LBank not as an exchange or a brand, but as an ecosystem.

Watch the full conversation: https://www.youtube.com/watch?v=bgMSfjc2Btw&t=1s